• TRUSTED RESEARCH

    TRUSTED RESEARCH | STRATEGIC INSIGHT

    SMB. CORE MIDMARKET. UPPER MIDMARKET. ECOSYSTEM
    LEARN MORE
  • COMMS, COLLAB, CONTACT CENTER

    COMMS, COLLAB, CONTACT CENTER

    SMB & Midmarket Buyers Collaboration, Contact Center Study
    LATEST RESEARCH
  • DATACENTER SOLUTIONS

    DATACENTER SOLUTIONS

    SMB & Midmarket Datacenter Solution Adoption Trends
    LATEST RESEARCH
  • PARTNER ECOSYSTEM

    PARTNER ECOSYSTEM

    CHANNEL PARTNER ECOSYSTEM TRENDS STUDY
    LATEST RESEARCH
  • BUYER JOURNEY

    BUYER JOURNEY

    SMB & Midmarket Buyers Journey Research
    LATEST RESEARCH
  • BUYER PERSONAS

    BUYER PERSONAS

    SMB & Midmarket Technology Buyer Persona Research
    LATEST RESEARCH
  • ARTIFICIAL INTELLIGENCE

    ARTIFICIAL INTELLIGENCE

    SMB & Midmarket Analytics & Artificial Intelligence Adoption
    LATEST RESEARCH
  • IT SECURITY TRENDS

    IT SECURITY TRENDS

    SMB & Midmarket Security Solutions Adoption Trends
    LATEST RESEARCH
  • 2026 TOP 10 SMB BUSINESS ISSUES, IT PRIORITIES, IT CHALLENGES

    2026 TOP 10 SMB BUSINESS ISSUES, IT PRIORITIES, IT CHALLENGES

  • 2026 TOP 10 SMB PREDICTIONS

    2026 TOP 10 SMB PREDICTIONS

    SMB & Midmarket: Autonomous Business
    READ
  • 2026 TOP 10 PARTNER PREDICTIONS

    2026 TOP 10 PARTNER PREDICTIONS

    Partner & Ecosystem: Next Horizon
    READ

Techaisle Analyst Insights

Trusted research and strategic insight decoding SMBs, the Midmarket, and the Partner Ecosystem.
Anurag Agrawal

Dell Leads the Way with Simplified PC Branding, Cutting Through the Confusion

In the ever-evolving world of personal computing, one thing has become abundantly clear: the market is saturated with confusing branding schemes from PC OEMs. The result? Decision paralysis for customers. At least, in the context of SMBs and Midmarket firms, Techaisle research finds that for 72% of firms, choice and complexity create decision inertia.  Dell Technologies, however, is taking a bold step forward, cutting through the noise with a new, simplified branding strategy designed to make choosing the right PC easier than ever before. This isn't just about a name change; it's about creating clarity, building trust, and leading the industry towards a future where technology is accessible and straightforward.

The Problem: PC Brand Overload

For too long, users have been bombarded with a bewildering array of PC brands, each with seemingly arbitrary naming conventions. The sheer number of brands, models, and features can make it incredibly difficult to discern which PC is the right fit. It's like walking into a grocery store with 50 brands of cereal, each with its own unique box and promises, making a simple breakfast decision an exhausting task.

This confusion creates what I call "decision inertia." Faced with too many options and not enough clarity, customers postpone their purchase or, worse, opt for a PC that doesn't truly meet their needs. This hurts both customers and PC manufacturers, which is a sign that the industry needs a change.

Dell’s Solution: A Clear Path Forward

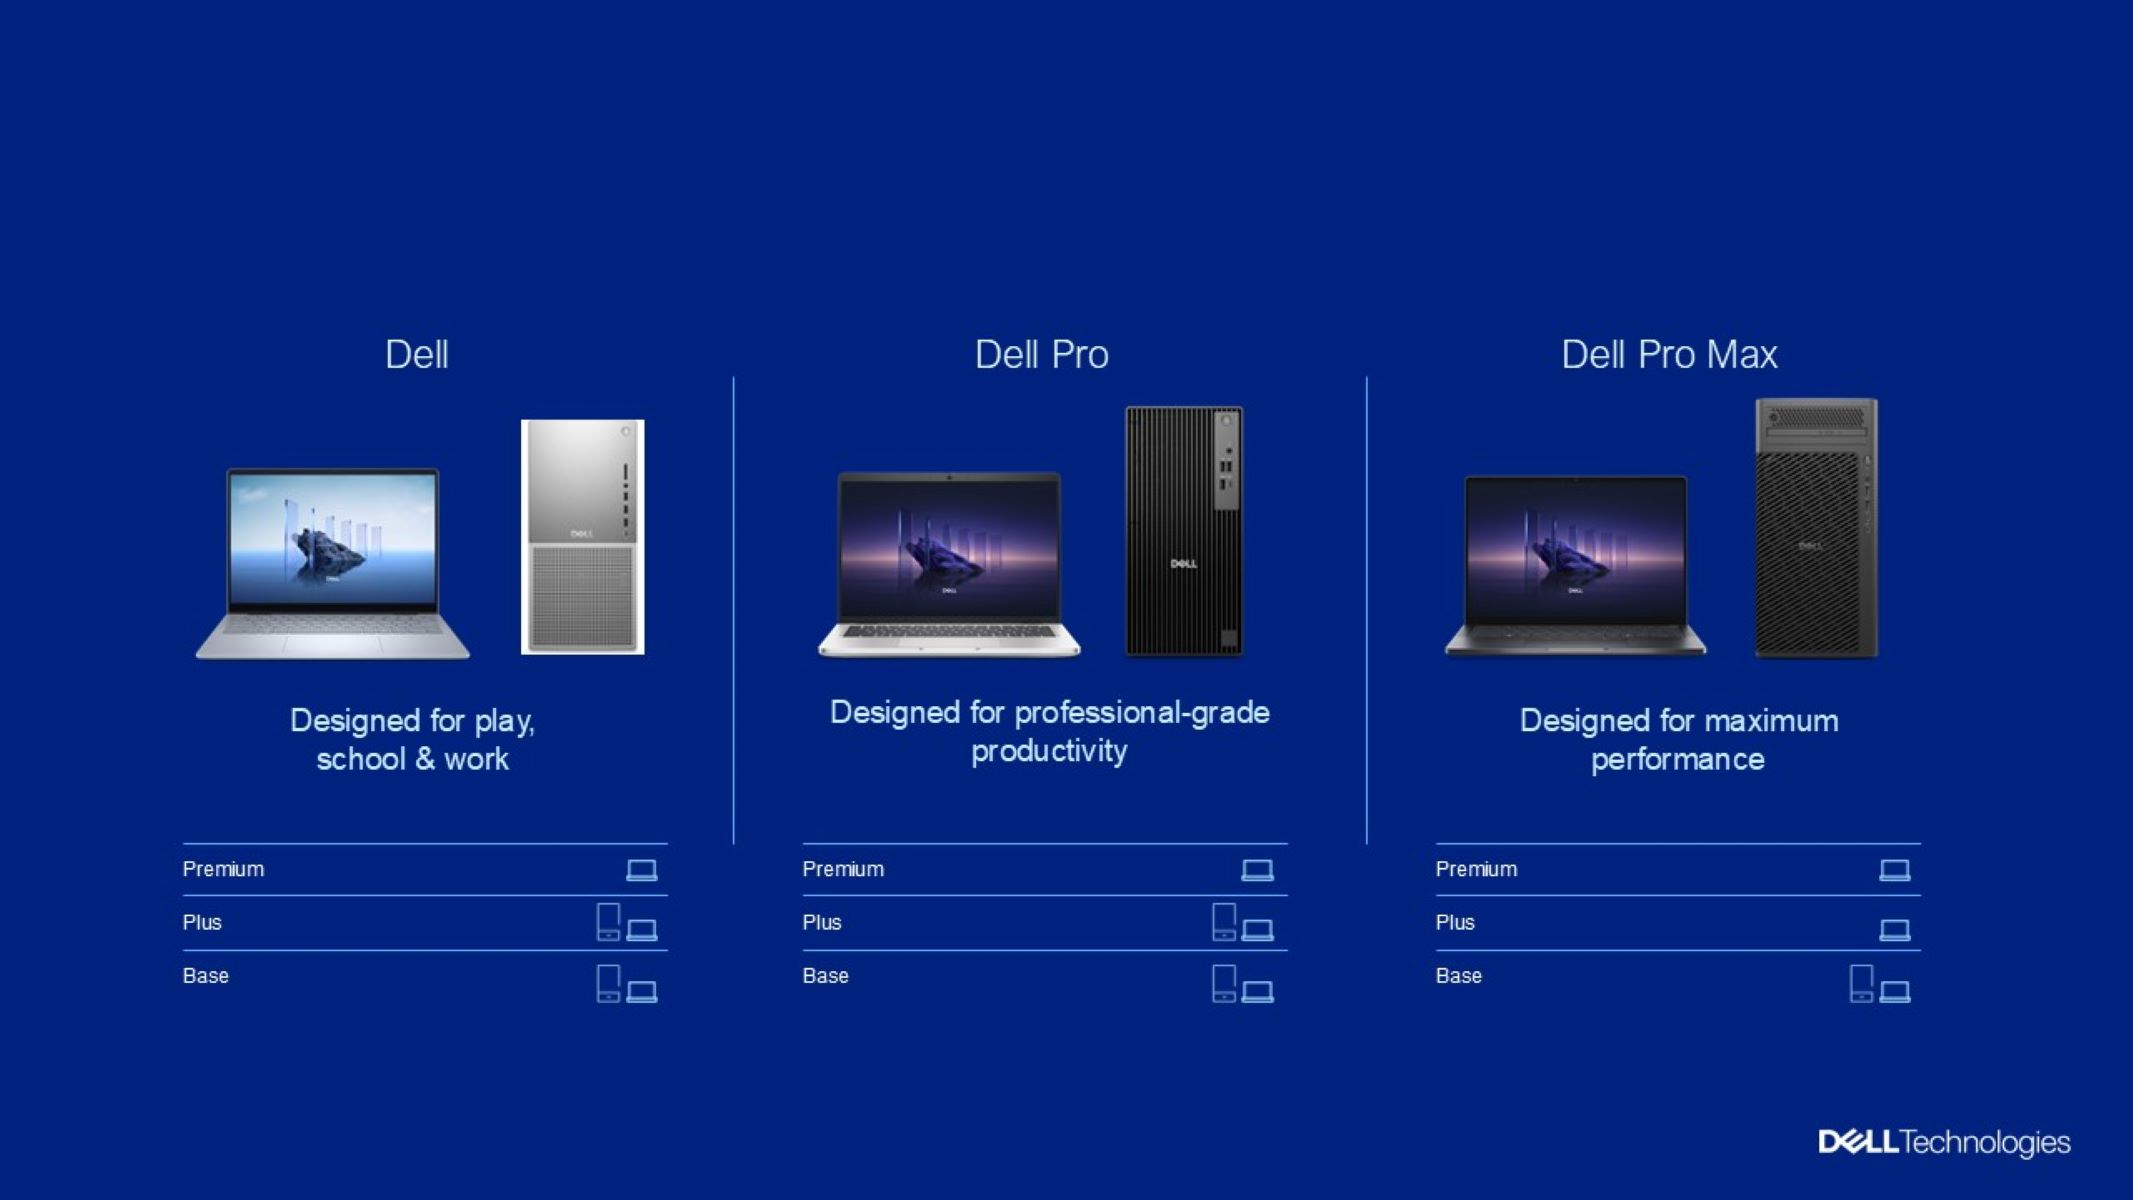
Dell's new branding strategy is a breath of fresh air in this chaotic landscape. Instead of adding to the confusion, Dell is simplifying its portfolio into three clear and distinct PC categories:

  • Dell: This category is designed for everyday users, encompassing laptops and desktops suitable for personal use, education, and light professional tasks. It's the "go-to" for reliable and affordable computing for individuals and families.
  • Dell Pro: This tier caters to professionals and businesses that require robust and secure devices for productivity and collaboration. This category offers laptops and desktops with enhanced security, durability, and manageability.
  • Dell Pro Max: This top-tier category is built for power users and demanding professionals who need maximum performance and cutting-edge technology. The Dell Pro Max lineup comprises high-performance workstations and laptops for complex workloads like content creation, data analysis, and scientific research.

This streamlined approach is more than just a name change. It is a commitment to providing customers with a clear understanding of what each category offers, making the buying experience more intuitive and less overwhelming. Putting the trusted "Dell" name front and center builds on decades of PC innovation and trust.

dell branding with tiers

The Merits of Simplified Branding

The move to a simplified branding strategy offers many benefits, not just for customers but also for Dell itself:

Tags:
Anurag Agrawal

A Comprehensive Look at Dell AI Factory and Strategies for AI Adoption

The rapid pace of AI innovation, coupled with the complexity of implementation, creates challenges for many businesses. Concerns around data security, intellectual property, and the high costs of running and managing AI models further complicate their AI journey. This is where Dell steps in, leveraging its extensive expertise in AI and innovative solutions to help businesses navigate these challenges. The company focuses on developing data management solutions, launching powerful computing hardware, and building partnerships to ensure businesses are equipped for the demands and opportunities of AI.

As part of its commitment to democratizing AI, Dell unveiled the Dell AI Factory at the recent Dell Technologies World (DTW) conference in May 2024. This unique initiative stands out for providing customers access to one of the industry's most comprehensive AI portfolio, from device to data center to cloud. The AI Factory, a distinctive combination of Dell's infrastructure, expanding partner ecosystem, and professional services, offers a simple, secure, and scalable approach to AI delivery. Its objective is to integrate AI capabilities directly within data sources, transforming raw data into actionable intelligence and thereby enhancing business operations and decision-making processes. In addition, Dell announced new channel programs to foster collaboration and accelerate AI adoption, recognizing the vital role of channel partners in driving revenue. With Dell's AI Factory, businesses can confidently embark on their AI journey, knowing they have a trusted partner to guide them every step of the way.

Understanding the AI Factory

To adopt AI on a large scale, a robust infrastructure is crucial. Conventional IT setups designed for regular computing often struggle to meet the complex demands of AI workloads. This is where the concept of an AI Factory becomes significant. Picture it as a specialized center with powerful computing systems, advanced data processing tools, and a team of AI experts. The AI Factory is designed to streamline AI solutions' development, deployment, and scaling, making it easier and faster. By consolidating these elements, an AI Factory ensures that AI innovations can be swiftly created and applied, reducing delays and increasing efficiency, thereby simplifying the complex process of AI deployment for businesses. With Dell's AI Factory, businesses can feel relieved of the implementation challenges, knowing they have a trusted partner to guide them every step of the way.

The Dell AI Factory simplifies AI deployment by offering essential components like servers, storage, and networking in one place. This streamlined approach eliminates the need for businesses to find and combine these components separately – and ensures they work well together, saving significant time and resources. Customers also gain access to Dell's AI expertise and a reliable ecosystem of partners. This comprehensive solution empowers businesses to choose from individual products or create custom configurations to fit their AI needs. The Dell AI Factory also offers different consumption models, including purchases, subscriptions, and as-a-service options, providing businesses the flexibility to adopt AI at their own pace. With Dell's comprehensive AI portfolio, businesses can feel secure knowing they have all the tools they need for successful AI adoption.

The Dell AI Factory is not just a collection of products. It is a comprehensive solution designed to simplify AI integration for businesses of all sizes.  Whether a business, like SMBs, is starting small with PCs or deploying AI across a server network, the Dell AI Factory equips the customers with the tools and expertise to achieve real-world results.

This powerful combination of high-performance infrastructure, industry-leading services, and deep AI knowledge can empower businesses to embrace AI confidently.  The Dell AI Factory goes beyond just hardware, offering a complete package that simplifies the entire AI adoption process, making Dell a key player in accelerating real-world AI applications. 

dell ai factory slide sg v6

Dell AI Factory Infrastructure

Training and deploying AI models require significant computational power and vast datasets. While convenient for many businesses, public cloud solutions can become expensive for these resource-intensive tasks and introduce security risks and the potential for IP infringement. Businesses increasingly seek on-premises solutions for greater control over data and resources and cost optimization. The Dell AI Factory addresses these challenges by providing a robust foundation built on Dell's core strengths in infrastructure solutions—servers, storage, data protection, and networking. This robust infrastructure delivers the necessary computational muscle and storage capacity for AI workloads.

Anurag Agrawal

AI PCs Poised for Takeoff in SMB and Midmarket Segments, But Snapdragon Faces Hurdles

A new type of computer is gaining traction: the Artificial Intelligence-powered PC, or AI PC for short.  At Microsoft Build 2024, Microsoft and its leading PC partners, Dell, HP, and Lenovo, unveiled a new class of laptops, Copilot+ PCs, explicitly built for artificial intelligence (AI).  These laptops are powered by powerful Snapdragon® X Plus processors, exceeding 40 trillion operations per second (TOPS), and deliver long-lasting battery life and access to cutting-edge AI models. 

The personal computer market is undergoing a significant shift, and small and medium-sized businesses (SMBs) and upper midmarket companies are paying close attention.  A recent study by Techaisle, covering 1410 SMBs and Midmarket firms in the US, suggests a potential surge in demand for these innovative machines within these business sectors. 

High Awareness Paves the Way for Adoption

The study reveals a high level of awareness and purchase intention among SMBs and midmarket firms, painting a promising picture of the market potential of AI PCs. A significant 77% of SMBs and an impressive 86% of upper midmarket firms are already familiar with AI PCs, demonstrating a high level of awareness and understanding of the potential benefits of AI technology for their productivity and operations. This awareness is not just passive, as the study reveals that a substantial 32% of SMBs and a much higher 64% of midmarket firms are actively planning to purchase AI PCs, indicating a strong market potential and the confidence these businesses have in the technology. This robust purchase intention signals a significant market shift and underscores the potential for widespread adoption in the near future. Moreover, 40% of SMBs are considering evaluating AI PCs before making a purchase decision, hinting at the possibility of even broader adoption in the coming years.

AI PCs are projected to dent the PC market within 3-5 years substantially. SMBs, known for their agility in responding to market trends, will likely mirror this trend. With 54% of SMBs planning to invest in new PCs in the next 12 months, AI PCs could become a decisive factor in purchasing decisions.

The study also uncovers some intriguing insights into SMB priorities. While 14% of SMBs view AI PCs as a crucial upgrade, and another 12% are considering a strategic shift towards them, a substantial portion (24%) see no compelling reason to adopt this new technology. However, 58% of SMBs report that their employees are actively requesting AI PCs. This highlights a potential disparity between management and employees regarding the perceived benefits of AI technology, suggesting the need for better communication and alignment.

The study identifies potential early adopters of AI PCs within the employee base. These are the content creators, tech-savvy departments, and executives in corner offices. Creative and design professionals top the list (45%), followed by IT development (27%) and sales and marketing teams (26%). These departments will likely benefit most from AI PCs' enhanced processing power and AI-powered features.

Copilot Gains Traction, But Snapdragon Faces Recognition Hurdle

The Techaisle study delves deeper, exploring the potential for Copilot, a new software solution designed to unlock the true power of AI PCs. Awareness is high, with over half (54%) of SMBs and a staggering majority (89%) of upper midmarket firms recognizing the name.  Despite its recent launch, nearly half of these businesses already know about Copilot+ PCs.

However, adoption intent dips regarding Copilot+ PCs powered by Qualcomm's Snapdragon processors. This hesitation stems from a few key factors. Limited brand awareness compared to the established giant Intel is a significant hurdle. Concerns about compatibility with existing applications and potential issues with peripherals further dampen enthusiasm. Many SMBs are adopting a wait-and-see approach, holding out for the announcement of Intel-based Copilot+ PCs, hoping these systems will offer similar features and impressive battery life.

Despite the growing hype around AI PCs, the study reveals some interesting realities regarding PC selection criteria for SMBs. While GPU/NPU might be a consideration, it does not reign supreme. For SMBs, the top five priorities when choosing a PC remain long battery life, a processor with built-in security features, ample storage capacity, a high-resolution display, and biometric login options.

Anurag Agrawal

Dell-EMC deal – sense and sensibility or solid reasoning

On October 12 Dell took an enormous step along its new chosen path of reorienting away from a provider of low-cost PC and server hardware to a role as a more sophisticated supplier to businesses that view technology as a strategic asset rather than as a tactical necessity. Dell announced a “definitive agreement” to acquire EMC (including EMC’s ownership positions in VMware, RSA Security, Pivotal Software, Virtustream and other industry firms and joint ventures) for $67 billion – the largest-ever acquisition in the information technology industry. The deal was announced to analysts and media in a conference call that featured Dell Founder and CEO Michael Dell, EMC President/CEO/Chairman Joe Tucci and Silver Lake Partners Managing Partner and Managing Director Egon Durban, and included VMware CEO Pat Gelsinger, Dell CFO Thomas Sweet, and David Goulden, who acts as CEO for EMC’s Information Infrastructure business.

Two second Take

The acquisition greatly enhances Dell’s position in higher-margin, higher growth markets: storage is expanding faster than servers or PCs, and EMC is focused on the higher-margin software used for device management as opposed to the creation of physical devices themselves.

Revenue Synergies – the $67 billion question

While the call eschewed any commentary on staff redundancies between the two organizations, it focused its messaging on “revenue synergies that are three times larger than cost synergies,” a justification for the deal that comes primarily from new growth opportunities rather than from squeezing out costs through headcount reductions.

It can be assumed that most of this growth potential comes from expanded market rather than product positioning. In his remarks, Michael Dell noted that Dell/EMC (including VMware) have already established “leadership positions in storage, servers, virtualization and PCs,” and have strength in IT’s “most important growth vectors,” including software-defined data centers, hybrid cloud, converged infrastructure, mobility and security – and are “positioned as a leader in an amazing 22 Gartner Magic Quadrants.”

If Dell and EMC are already leaders in all of these large and/or expanding areas, then the question is where will further growth come from? It appears that the combined entity is banking on the benefits associated with increased customer account presence. In particular, Michael Dell noted that “as the data market moves to a compute-centric, converged model, Dell’s server franchise is a natural fit with EMC’s strength.” The theory appears to be that by combining EMC’s prowess at selling to enterprise accounts and Dell’s broader compute portfolio the company can increase share of wallet within major accounts; there is also some opportunity for using EMC to drive increased storage presence within Dell’s “growing commercial infrastructure franchise” in the SMB base, but this is likely to be a secondary consideration.

Security, Converged Infrastructure, Mobility, Big Data

Dell has been investing heavily in building a comprehensive security portfolio, assembling advanced threat identification services firm SecureWorks (acquired by Dell in 2011), firewall/unified threat management from vendor SonicWALL (acquired in 2012), backup software specialist AppAssure (2012) and identity monitoring and management software vendor Quest (also acquired in 2012), plus related capabilities sourced from thin client vendor Wyse (purchased by Dell in 2012) and from work done by Dell’s own engineering team. With the latest acquisition Dell adds encryption pioneer RSA Security (which became a division of EMC after being acquired in 2006) and enterprise mobility management supplier AirWatch (acquired by VMware in 2014), thus diversifying the portfolio even more. Dell has been positioning end-to-end security as a differentiating feature of its infrastructure portfolio for some time and with the acquisition Dell’s security story becomes even stronger, and even more distinct from the approaches of competitors like Lenovo, HP and Oracle.

Although it is tempting to look at a Dell/EMC/VMware combination as a means of consolidating a converged infrastructure offering capable of competing with the Cisco-led Vblock (Cisco, EMC, VMware) and FlexPod (Cisco, NetApp, VMware) offerings, it appears that Dell’s vision is broader and more strategic.

The acquisition also gives Dell a foothold into the big data deployment market opportunity where the enterprise spending is still hardware driven rather than software and analytics uptake.

And with AirWatch in the mix, Dell finally gets a mobility story in place beyond just the mobile devices.

Move to cloud

Michael Dell believes that “the combined company is very well positioned to address the move to the cloud,” both by providing infrastructure to public cloud providers and private cloud operators and through VMware’s ability to enable hybrid cloud. But in his remarks, he went further, observing that “I think what you’re seeing with the Software Defined Data Center is an ability to take the benefits of the public cloud and bring them into an on-premise data center.” He considers the complexities associated with connecting compute, network and storage as a major demand driver for public cloud, and virtualization and converged infrastructure as a means of delivering greater simplicity in on-premise environments, allowing firms to focus on optimizing for “the application user, quality of service and security.”

But Michael Dell is not satisfied by simply focusing on leveling the terrain between cloud and on-premise infrastructure, his vision is to supply infrastructure across different environments (public clouds, SaaS, hyperclouds, private clouds), providing common, connected and secure platforms to customers of all sizes, wherever their IT workloads reside.

Financial challenges

A lot has been said and written about financial challenges but due to the enormity of the deal size it is worth another read, from our point-of-view. The cost of debt may have an impact on the overall cost of operating the newly-expanded Dell entity. Dell was thought to have about $12 billion in debt prior to this deal; clearly, this figure will increase substantially after the acquisition. Michael Dell did state that observers could expect “a significant deleveraging” resulting from cost savings, increased revenue and cash flow management improvements that come with being a private company, but $67 billion represents a very high hurdle for these activities. Obtaining the funds themselves is not an issue but it seems likely that the costs associated with debt service may affect product prices and margins, and it is difficult to boost either in many of Dell’s core hardware markets. It might well be that asset sales become important to enhancing corporate profitability by reducing the cost base of the company.

Should debt reduction become a priority, the newly-expanded Dell would have a few options, starting with VMware. Although there was no mention of selling VMware as part of this deal – indeed, VMware CEO Pat Gelsinger was described as having a “very bright future” in the new organization – EMC’s 80 percent stake in VMware is worth more than $26 billion at current valuations. It will be very tempting to convert this equity into reduced debt to help the competitiveness of future hardware products, though this would be at the cost of an ownership position that (as per the terms of the Dell deal) accounts for 40 percent of EMC’s overall value. There are other avenues Dell could pursue – for example, it could combine its in-house security assets with RSA, and perhaps AirWatch, to create a stand-alone security business that could be monetized via issuance of public market shares – but a VMware sale is clearly the most direct means of raising capital to reduce debt.

Go-to-market challenges

An often-overlooked ingredient in a merger is the extent to which go-to-market staff and strategies can be melded in a single organization. This will likely be a significant issue for the expanded company. Dell and EMC customer-facing staffs have very different skills and compensation levels and may not be neatly amalgamated into a single sales force. The channel strategies of the two firms are different as well. Because EMC has focused primarily on large deals within large accounts and Dell has been more SMB (and consumer) focused, it may be that the sales staff and channel strategies can be aligned by sector but that will not erase the GTM discrepancies.

EMC sales staff work large, high margin deals, and are among the best compensated reps in the industry; Dell certainly cannot afford to reduce EMC-classic rep compensation (which would trigger a mass exodus to competitive startups) or to pay EMC rates to Dell-classic sales staff (which would consume more than 100 percent of current margins). From a channel and alliance perspective, EMC is a strategic partner to its enterprise-level services and software partners; Dell is primarily a tactical resource for SMB-focused VARs and integrators. These approaches target different partners with different programs and are delivered in different ways. Again, it is possible to align strategies by market sector, but many partners are likely to try to “shop” across programs to “Frankenstein” together blends of services and compensation structures that optimize the supplier benefits that they derive from the new Dell, and some – notably, Cisco, which is an EMC ally via Vblock – will find a Dell partnership untenable.

Final Take

While there are reasons to admire Dell’s strategy, it is very rare to find successful examples of a merger yielding a combined market presence that eclipses the individual positions of the firms involved. However, these are still early days, and the hard decisions will not be made until mid-2016, but there are still many operational issues to be ironed out between now and then. Even though Dell is not a public company, it will need to explain its expectations of “revenue synergies” to customers, analysts and the press, and Silver Lake will likely need to do the same for its current and potential investors.

There are reasons to both admire and to question the Dell/EMC deal. The answer to the $67 billion question will be found in the opportunities for “revenue synergies” that extend well beyond today’s converged infrastructure SKUs, and into the cloud and the core operating models of customers ranging from EMC’s traditional public sector and large enterprise accounts to Dell’s SMB buyers. If Dell can extend its reach across the full spectrum of IT/business infrastructure, it may build a position as the behemoth HP believed it would become, before it was bifurcated into two distinct business units. If it does not, it may more closely resemble Oracle, trying to assemble a coherent vision from a series of mismatched pieces.

The real winner though is Silver Lake. It has positioned itself as a central force within the technology industry, an unusual position for a private equity firm, and may signal that excellence in financing is joining excellence in inventing technology and excellence in technology marketing as paths to the industry’s pinnacle.

Tags:

Trusted Research | Strategic Insight

Techaisle - TA