• TRUSTED RESEARCH

    TRUSTED RESEARCH | STRATEGIC INSIGHT

    SMB. CORE MIDMARKET. UPPER MIDMARKET. ECOSYSTEM
    LEARN MORE
  • COMMS, COLLAB, CONTACT CENTER

    COMMS, COLLAB, CONTACT CENTER

    SMB & Midmarket Buyers Collaboration, Contact Center Study
    LATEST RESEARCH
  • DATACENTER SOLUTIONS

    DATACENTER SOLUTIONS

    SMB & Midmarket Datacenter Solution Adoption Trends
    LATEST RESEARCH
  • PARTNER ECOSYSTEM

    PARTNER ECOSYSTEM

    CHANNEL PARTNER ECOSYSTEM TRENDS STUDY
    LATEST RESEARCH
  • BUYER JOURNEY

    BUYER JOURNEY

    SMB & Midmarket Buyers Journey Research
    LATEST RESEARCH
  • BUYER PERSONAS

    BUYER PERSONAS

    SMB & Midmarket Technology Buyer Persona Research
    LATEST RESEARCH
  • ARTIFICIAL INTELLIGENCE

    ARTIFICIAL INTELLIGENCE

    SMB & Midmarket Analytics & Artificial Intelligence Adoption
    LATEST RESEARCH
  • IT SECURITY TRENDS

    IT SECURITY TRENDS

    SMB & Midmarket Security Solutions Adoption Trends
    LATEST RESEARCH
  • 2026 TOP 10 SMB BUSINESS ISSUES, IT PRIORITIES, IT CHALLENGES

    2026 TOP 10 SMB BUSINESS ISSUES, IT PRIORITIES, IT CHALLENGES

  • 2026 TOP 10 SMB PREDICTIONS

    2026 TOP 10 SMB PREDICTIONS

    SMB & Midmarket: Autonomous Business
    READ
  • 2026 TOP 10 PARTNER PREDICTIONS

    2026 TOP 10 PARTNER PREDICTIONS

    Partner & Ecosystem: Next Horizon
    READ

Techaisle Analyst Insights

Trusted research and strategic insight decoding SMBs, the Midmarket, and the Partner Ecosystem.
Anurag Agrawal

The Midmarket AI Fracture: Why the Infrastructure Supercycle Demands Full-Stack Orchestration

For decades, midmarket infrastructure procurement followed the hardware-aging cycle: IT departments replaced servers and switches as they depreciated. In the upper midmarket, that cycle has broken. According to the Techaisle SMB and Midmarket Datacenter Solutions Adoption Trends Research Report, 57% of the overall SMB market has a major infrastructure refresh underway or scheduled within 12 months, and in the upper midmarket the primary catalyst is now proactive workload enablement rather than hardware aging.

The data gravity of artificial intelligence is driving a hardware supercycle. 32% of upper midmarket firms are refreshing to meet new workload requirements, including AI, against 20% replacing hardware at end of life. In the core midmarket, end-of-life replacement still leads at 28%. The supercycle is creating distinct architectural tracks based on organizational maturity, and major ecosystem players such as Dell, Lenovo, Cisco, AWS, and Google Cloud need to reevaluate how they position their portfolios for each. The disjointed accumulation of isolated products has created an integration gauntlet, and midmarket customers are demanding cohesive, full-stack orchestration.
techaisle midmarket ai fracture

Anurag Agrawal

Vendor Channel Programs Are Simplifying Faster Than They Are Stabilizing

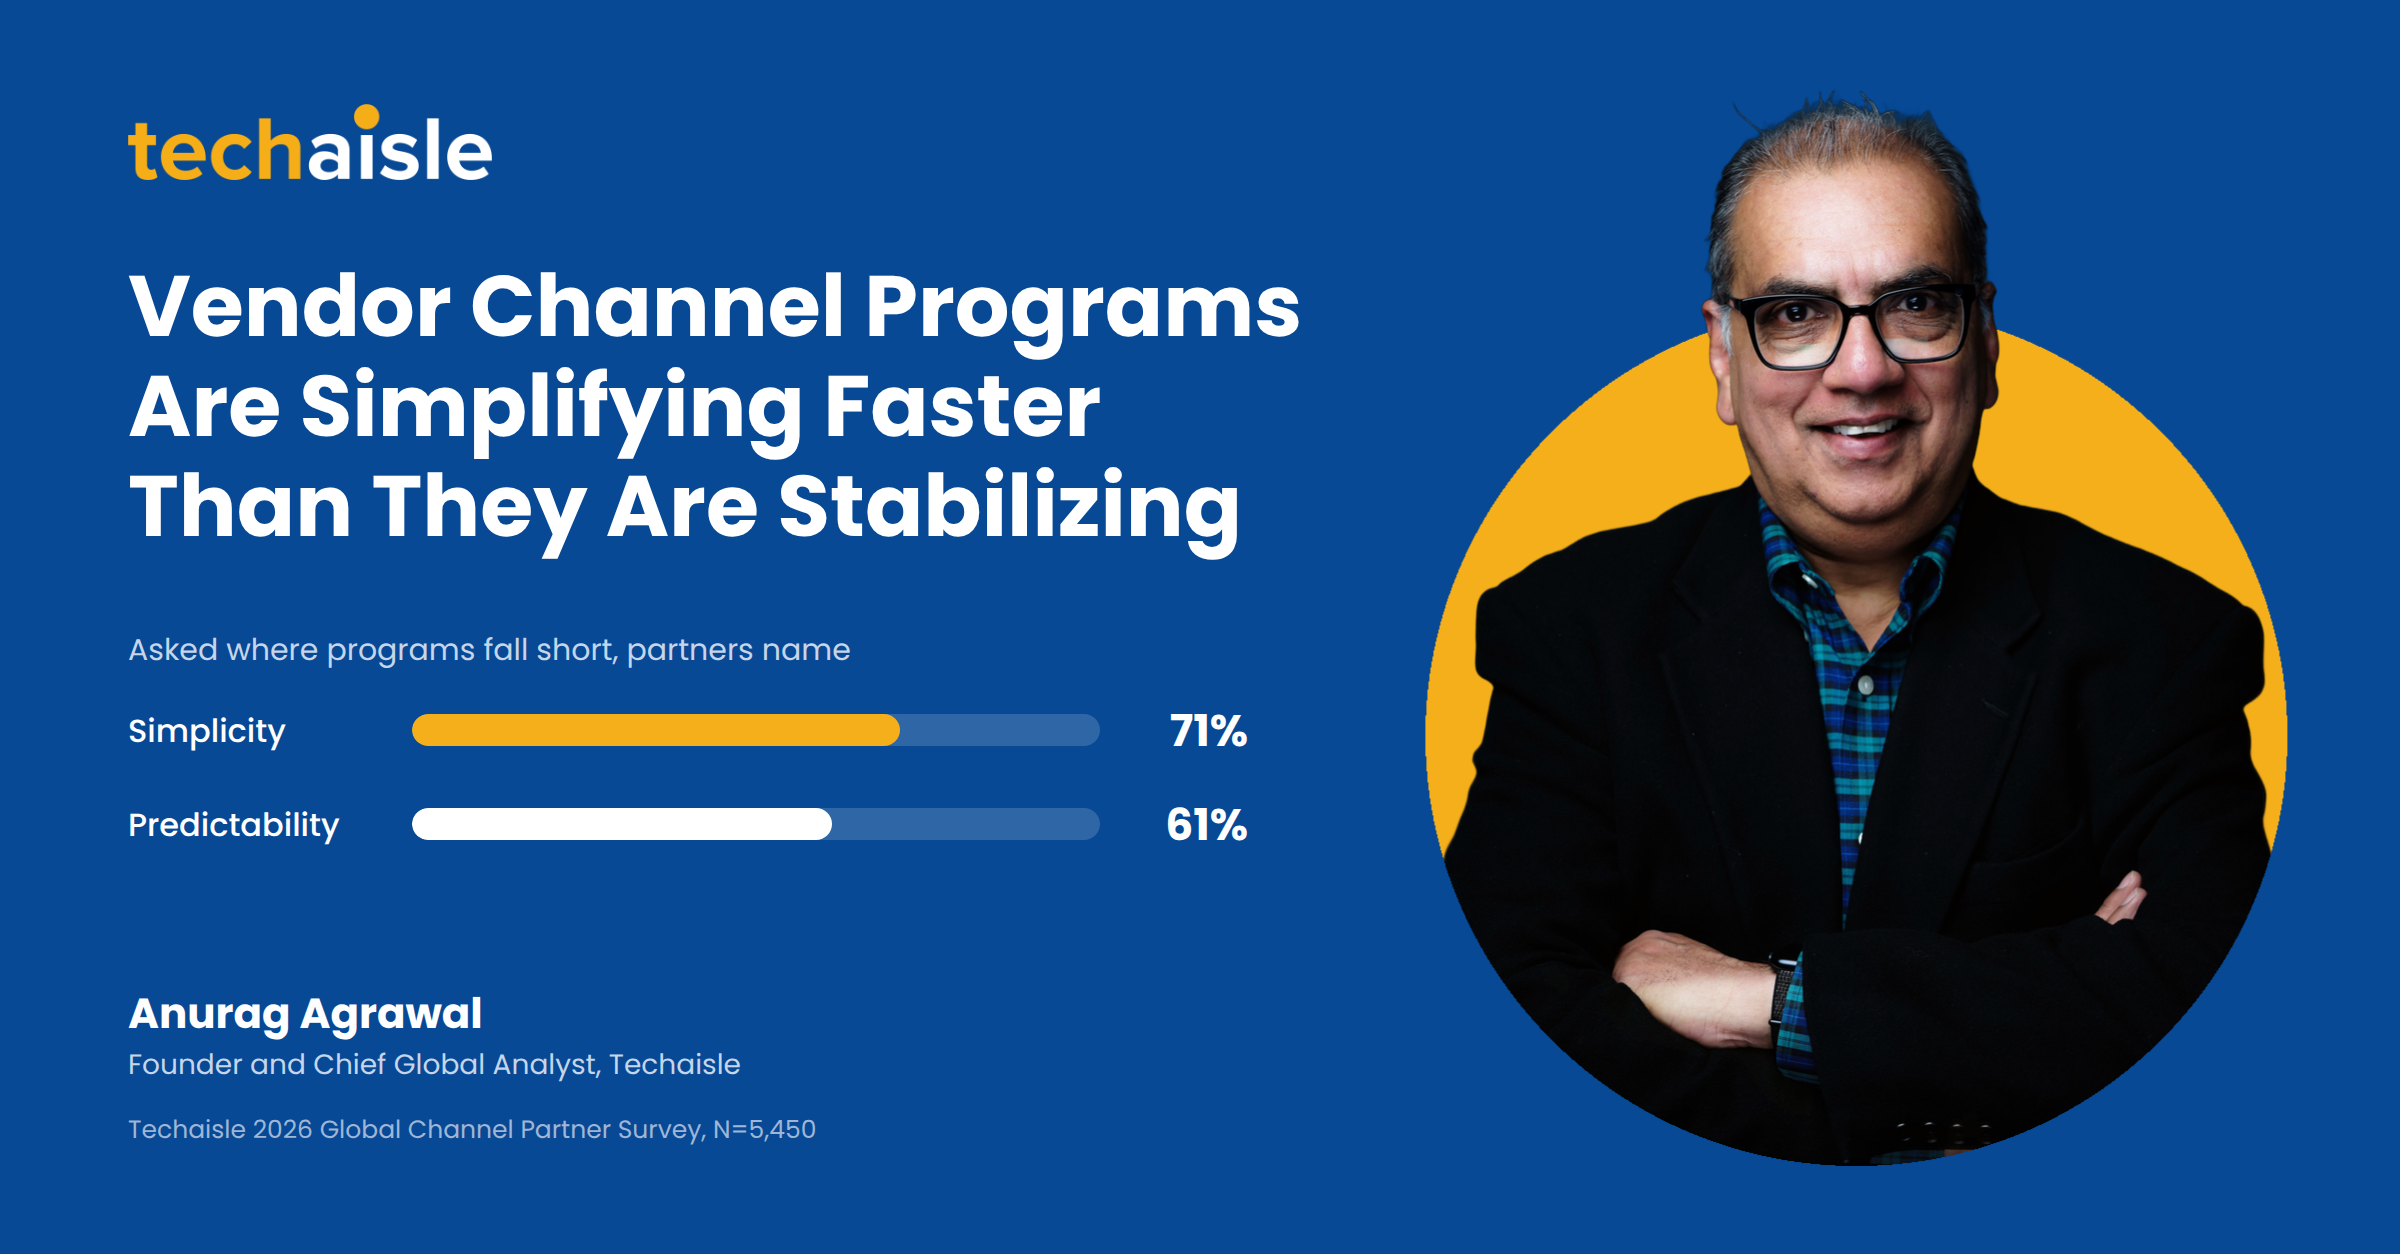
Channel partners were specific when Techaisle asked what a vendor program should deliver. In our 2026 survey of 5,450 channel partner firms, 88% rate profitability as critical or very important, and 78% say the same about predictability. Strategic value ranks last at 69%. Asked where programs fall short, partners name simplicity first (71%) and predictability second (61%). Predictability is one of the attributes partners value most and one of the two where programs fail most often.

Many of the largest vendors have rebuilt their partner programs over the past 2 years. Some of those changes line up with what partners asked for, and a few work against it. Across the 2026 changes from AWS, Cisco, Microsoft, Google Cloud, Dell, HPE, Lenovo, Palo Alto Networks, and Broadcom, one pattern stands out: programs are getting simpler faster than they are getting predictable. Most of the work went into fewer tiers, merged incentives, and automated paperwork, while the changes that cost partners money came from timing.

Techaisle calls this gap the Incentive-Trust Deficit. Partners will accept thinner margins in exchange for rules that hold for a year. For a vendor, that makes predictability a cheaper lever than a richer rebate. For a partner, a vendor's record of program changes matters as much as its margin structure when deciding where to commit staff.

Anurag Agrawal of Techaisle beside the headline Vendor Channel Programs Are Simplifying Faster Than They Are Stabilizing, with a bar chart showing partners name simplicity (71%) and predictability (61%) as where vendor programs fall short

Anurag Agrawal

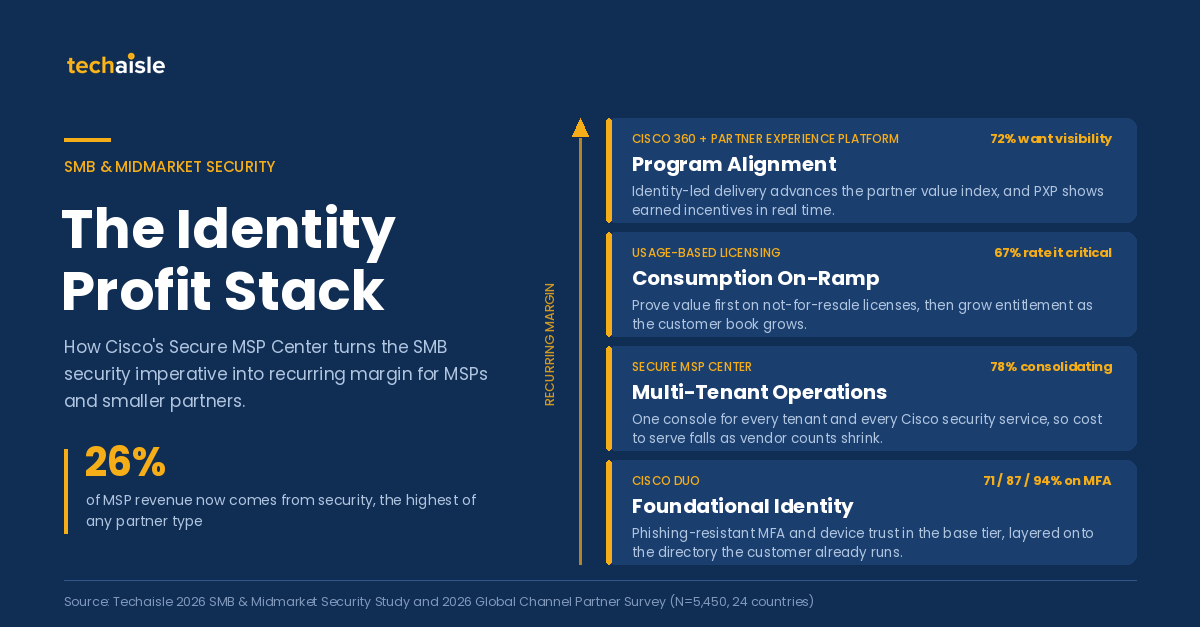
The Identity Profit Stack: How Cisco’s Secure MSP Center Turns the SMB Security Imperative into Recurring Margin

For partners serving the SMB and midmarket, the security conversation has changed in a way that resets the profit equation. Security has stopped being a discretionary line item that customers fund when they get around to it. The reason is not abstract. Identity-related attacks have moved to the center of how breaches happen, and attackers armed with stolen credentials and AI-assisted social engineering increasingly bypass multi-factor authentication by logging in rather than breaking in. The control surface that buyers most need to defend has shifted from the network to the identity itself, and the budget is following suit.

Techaisle’s 2026 SMB and Midmarket Security study shows that the organizations these partners serve are not only spending more on security, but also restructuring how they buy it. Over 60% of Core Midmarket organizations plan to increase security budgets by 5% or more in 2026, and 28% of the Upper Midmarket plan to increase budgets by more than 15%. The pattern reads as a structural reset rather than a fear-driven spike. Buyers have accepted that breach inevitability has moved downmarket, and that identity is now the control surface that matters, which is why protecting the identity plane ranks as the single highest security priority across the SMB market.

For the smaller partner and the MSP, that reset is the largest unclaimed annuity in the channel. The question is whether the partner has the architecture to capture it.

techaisle cisco identity profit stack

Tags:
Anurag Agrawal

Cisco IQ: Repricing the Economics of Infrastructure Support

On Monday morning, 1st June, 2026, a total of 1,500 customers had self-onboarded onto Cisco IQ. By evening, it was 1,600. Tuesday morning, 1,700. By the time I left Cisco Live 2026 in Las Vegas, Tuesday evening, I was told the number had crossed 2,000.

But I am getting ahead of myself.

The Constraint Cisco IQ Removes

Enterprise support has been a reactive business for twenty years, and not for lack of ambition. It was reactive because it was blind. Between audits, no vendor had an accurate, up-to-date picture of what a customer was running, which devices were exposed, and which had drifted out of compliance. Support waited for the failure and billed to fix it. That blindness, not the absence of AI, is the constraint that defined the category.

Cisco IQ removes the constraint. At its simplest, it is an intelligence layer that sits over a customer’s entire Cisco estate. Strip away the module names, and what it does is make that estate continuously legible. It fuses asset telemetry pulled from the live network, contract and entitlement records, and two decades of support history into a single, always-current model of what the customer runs, and it reasons over that model without waiting to be asked. The AI is the visible part, but it sits atop the harder thing: a reconciled, constantly updated model of the estate. That model is what competitors cannot easily reproduce, because it is built from years of data rather than shipped as a feature.

techaisle cisco cx writeup

Tags:

Trusted Research | Strategic Insight

Techaisle - TA